A 48.5% quarterly revenue surge sits uneasily beside Seagate’s five-year annualised growth of 2.7%. The company reported $3.63 billion in revenue and adjusted earnings per share of $5.71 for the quarter, beating analyst estimates and pointing to strong demand from AI-driven cloud data centres, Reuters reported on July 28, 2026. Management lifted next-quarter guidance to a midpoint of $4.1 billion, above the LSEG consensus of about $3.75 billion, and said HAMR technology is helping pack more capacity per disk. For investors and cloud operators the result is both relief and a new test: can HDD makers turn this AI cycle into sustained multi-year growth?
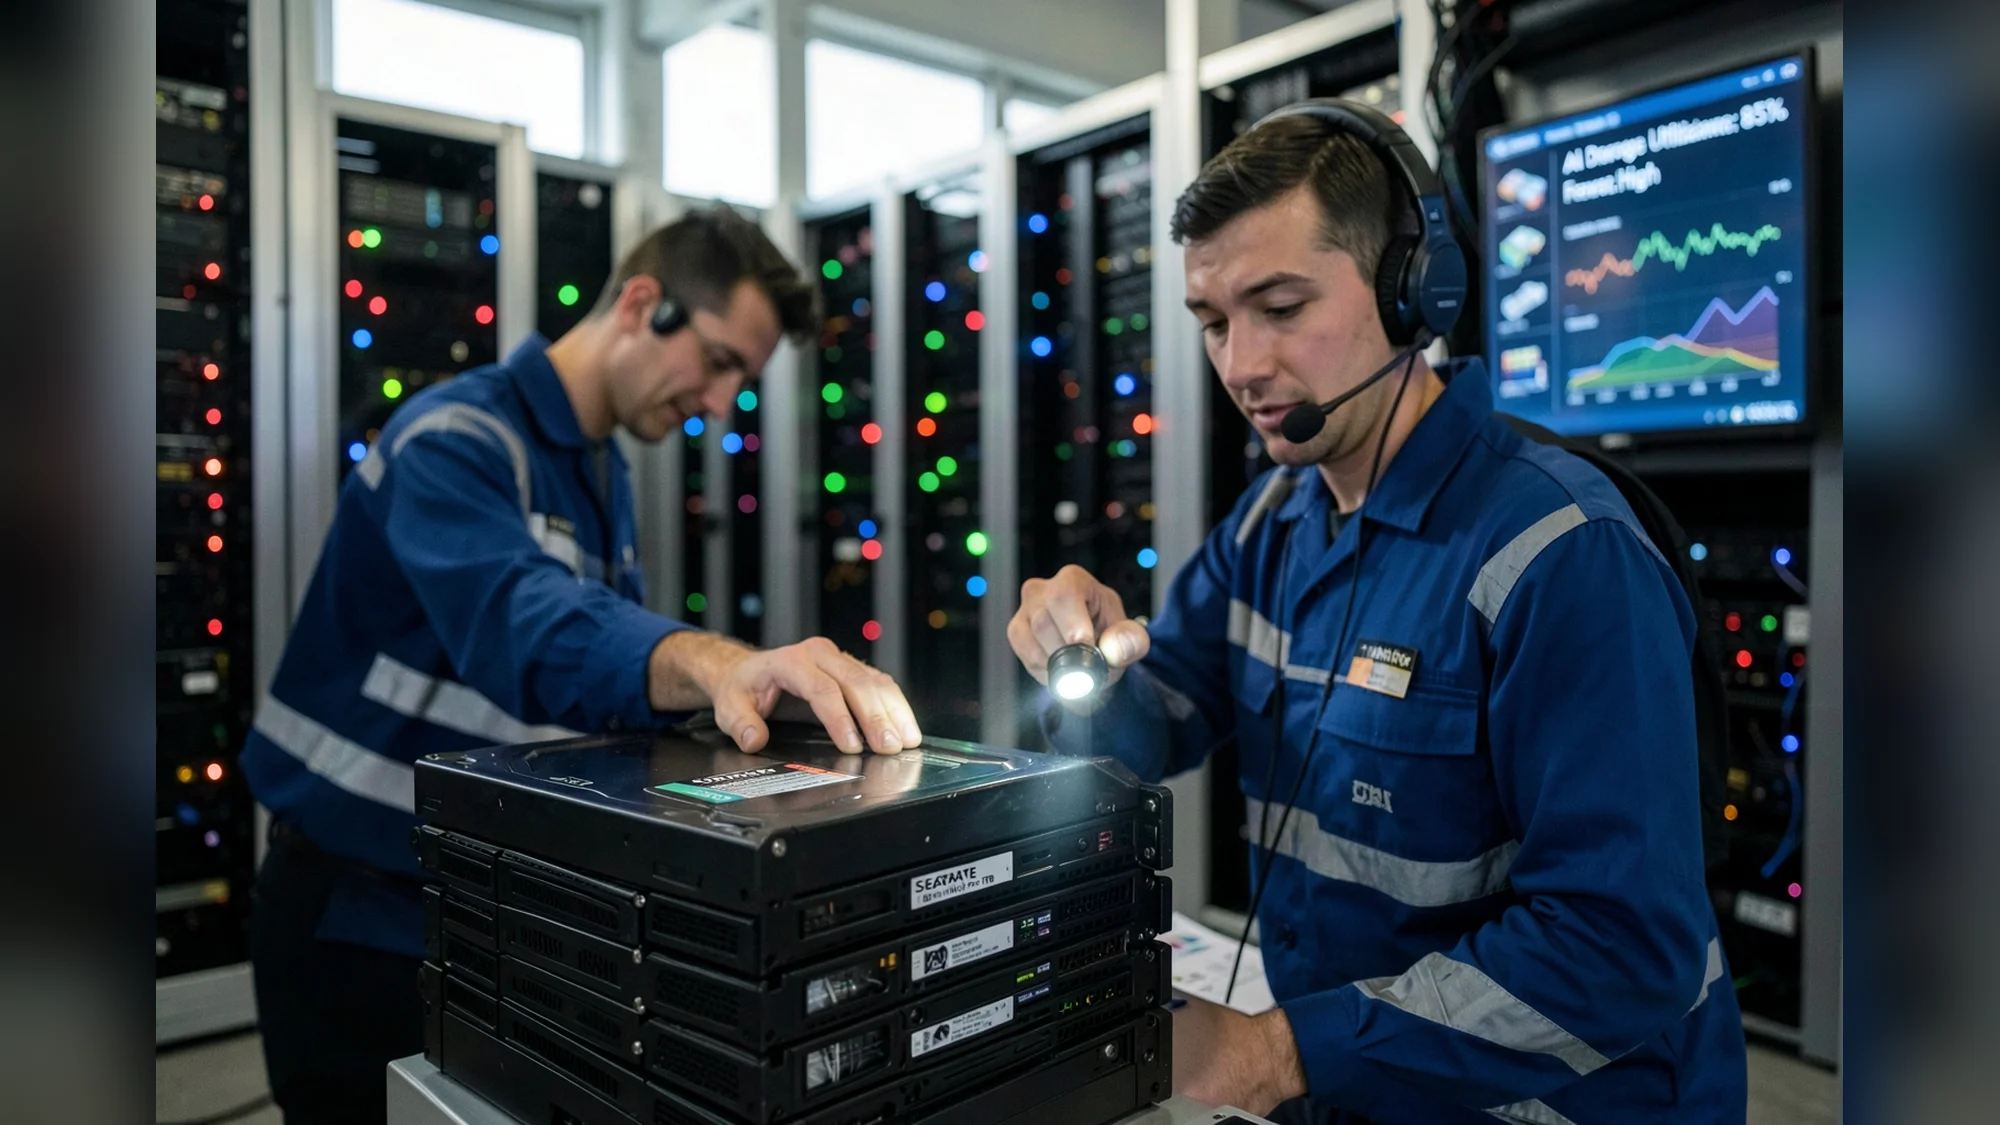
The beat was dramatic, but the strategic question is straightforward. Seagate’s quarter was powered by a near-term boom in demand for high-capacity nearline hard disk drives as generative AI workloads push cloud providers to store vastly larger datasets. Reuters reported the numbers and outlook on July 28, 2026, noting Seagate’s adjusted EPS of $5.71 beat an analyst consensus of $5.09.
What moved the numbers
Seagate booked $3.63 billion in revenue for the quarter, up 48.5% year on year, and guided to $4.1 billion at the midpoint for the next quarter with a margin of plus or minus $100 million, Reuters said. The company also guided adjusted profit of $7.30 per share at the midpoint, plus or minus $0.20, versus an LSEG analyst average near $5.80 per share. Reuters added that shares rose more than 8% in after-hours trading and that Seagate’s stock had more than doubled year to date.
The company attributed the strength to take-up of higher-density drives enabled by heat-assisted magnetic recording, or HAMR, which management says allows Seagate to lift capacity without building equivalent new factories. Management told investors the firm generated record free cash flow during the fiscal year and that annual revenue rose 34% in the period. TradingView and 247WallSt reported wider margins and stronger cash generation in the quarter, with adjusted EBITDA and operating margins swinging materially from the prior year.
Why investors must test repeatability
The market reaction shows one simple point. Cloud customers are willing to accept nearline HDDs and to qualify newer, higher-density technologies when the buildout calculus favours cheaper mass storage. Reuters described AI infrastructure buildouts as the key demand signal. That has let Seagate raise prices and capture operating leverage, and it handed investors short-term comfort.
But the longer record makes the narrative. TradingView noted Seagate’s five-year annualised revenue growth is only 2.7%, even as the company recorded 36.4% annualised growth over the last two years. 247WallSt and Yahoo cast the quarter as evidence that nearline capacity is becoming a material revenue segment for Seagate, while also flagging two principal risks to sustaining current growth rates: competition from solid-state drives and the pace at which customers qualify new HDD technologies.
Put differently, the quarter answers a buildout question and opens a new one. First, demand and pricing are strong now. Second, investors must decide whether those gains will persist once the current cycle matures. The improved margins and record cash flow are real, but they must be repeatable across cycles to change the company’s multi-year growth profile.
Related Articles
The immediate test for investors is whether Seagate can meet its guidance of $4.1 billion in revenue and $7.30 adjusted EPS at the midpoint next quarter, numbers that will show if the AI-driven demand surge can alter the company’s modest five-year growth trajectory.
This article was created with AI assistance.