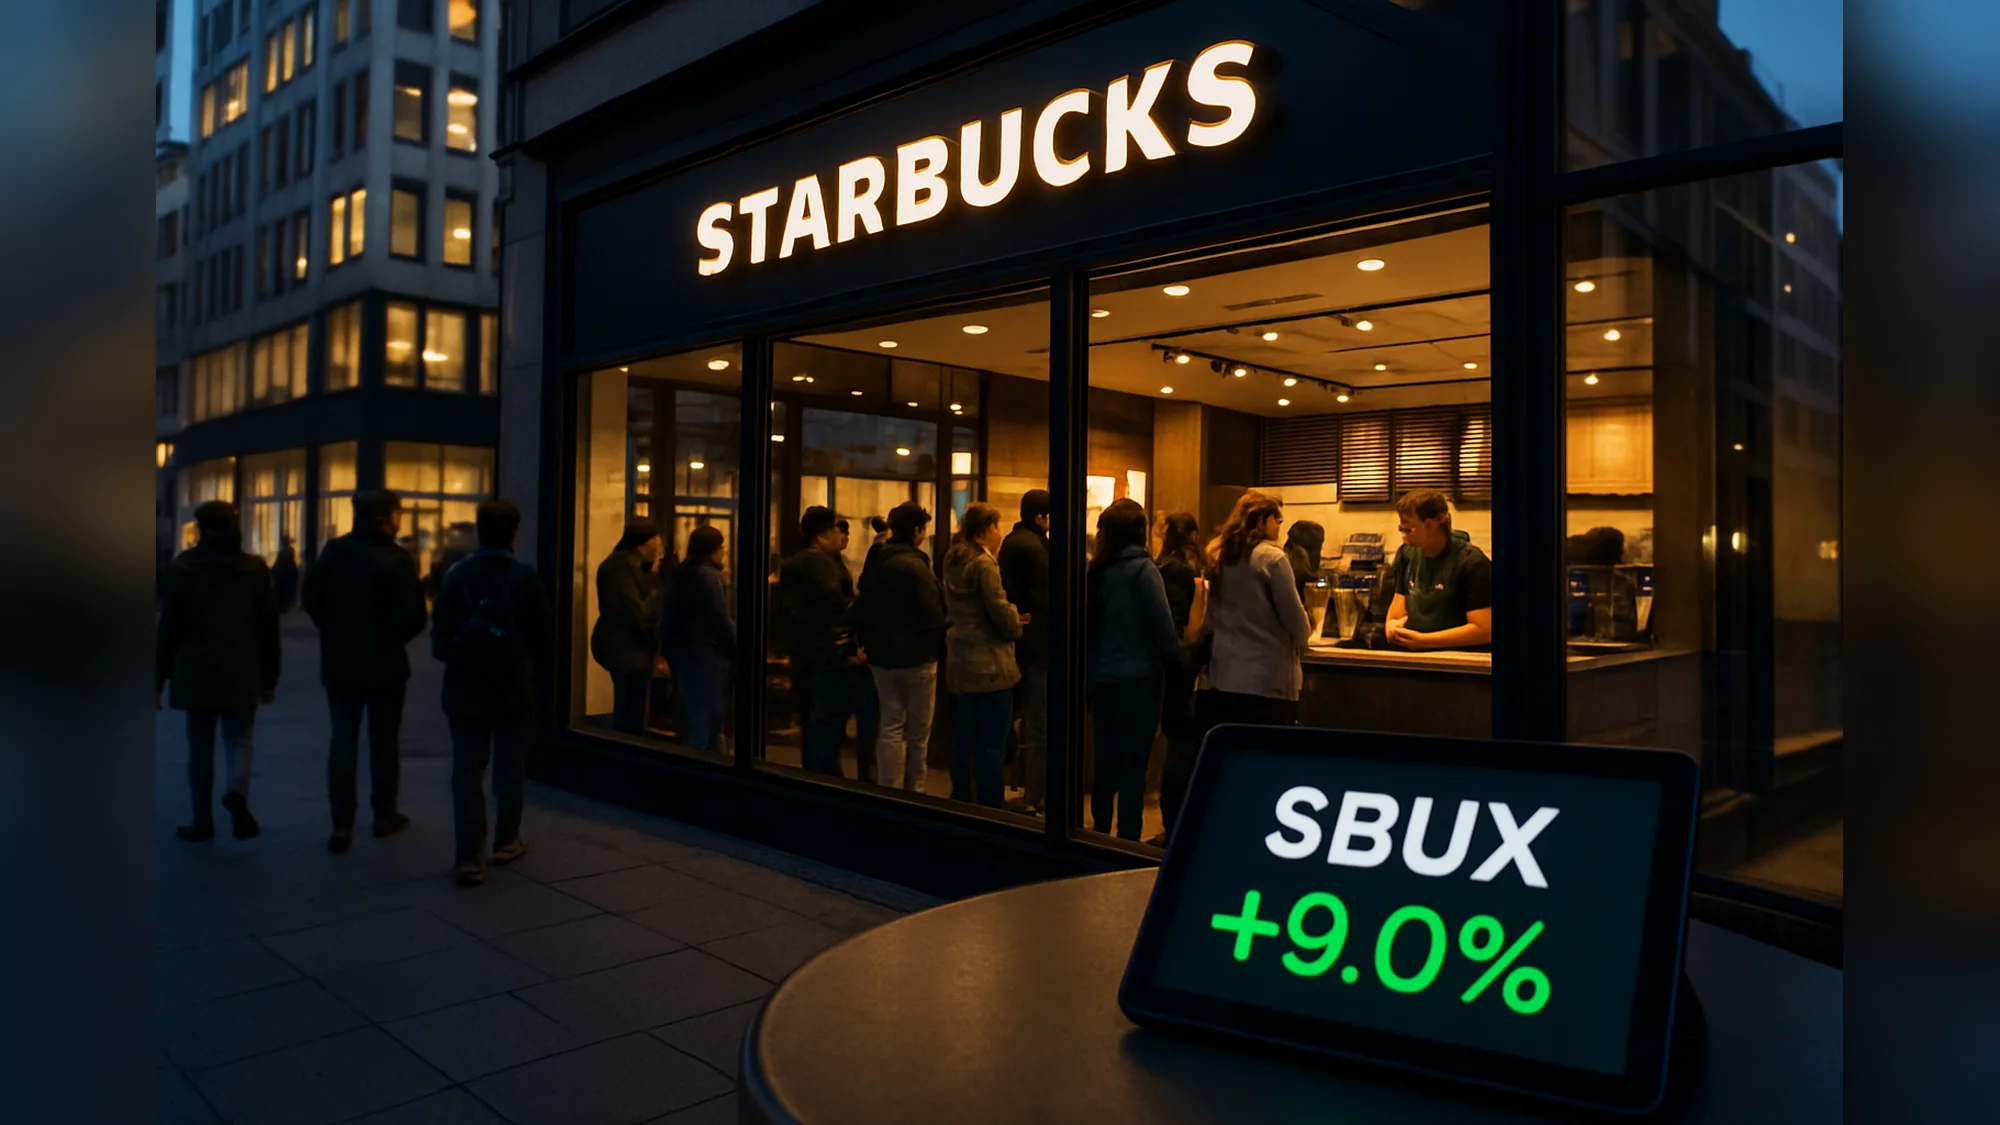
9%. That's how much Starbucks shares surged in extended trading on July 29 after the company beat quarterly expectations and upgraded its full-year outlook. The coffee chain raised adjusted EPS guidance for fiscal 2026 to $2.55 to $2.65 from a prior $2.25 to $2.45 range, and reported global comparable-store sales up 7.9% for the quarter ended June 28. The move matters because management tied the improvement to its Back to Starbucks strategy and said momentum is now measurable, even as revenue fell 1% year on year following the sale of a controlling stake in China.
7.9%. That's how much global comparable-store sales climbed in Starbucks fiscal third quarter, the company's fourth consecutive quarter of comp growth and the central reason management lifted its full-year targets. North American same-store sales rose 8.1% in the quarter, with transactions up 4.5% and average ticket up 3.5%, signalling more visits and higher spend per visit.
Revenue for the quarter ended June 28 was $9.32 billion, a 1% decline year on year that Starbucks said reflected the previously announced transaction transferring control of its China retail operations rather than a drop in demand. The $9.32 billion figure beat the LSEG consensus revenue estimate of $9.16 billion.
Profitability also surprised to the upside. Adjusted earnings per share were $0.85, ahead of LSEG expectations of $0.66. On a GAAP basis, net income attributable to Starbucks rose to $1.05 billion, or $0.91 per share, compared with $558.3 million, or $0.49 per share, a year earlier. Management pointed to operating margin expansion to 13.6% in the quarter from 13.3% a year earlier, helped in part by tariff refunds received during the period.
"The refunds we received in Q3 largely offset related tariffs incurred in the first three quarters of fiscal 2026," Cathy Smith, chief financial officer, said on the company's earnings call.
Chief executive Brian Niccol described the quarter as the point when the company's momentum became measurable, saying in the earnings video, "This was the quarter our momentum became truly measurable." Starbucks attributed the improvement to a mix of investments in store experience, labour and targeted menu innovation. Management pointed to strength in limited-time summer drinks, and noted it has renovated more than 1,000 stores in North America with plans to complete another 500 before the fiscal year ends on September 28, 2026.
The company raised its full-year same-store sales guidance to nearly 6% globally and to more than 6% in the United States, up from previous forecasts of at least 5% growth for both measures. It also upgraded its adjusted EPS outlook for fiscal 2026 to a range of $2.55 to $2.65, from the earlier $2.25 to $2.45 range. Those revisions, together with two consecutive quarters of margin expansion and four consecutive quarters of comp growth, formed the rationale management gave for the stronger guidance and the market's positive reaction.
Analyst context amplified the share move. Polling from StreetAccount and FactSet cited in coverage had set expectations for weaker comps and revenue than Starbucks delivered, which helped drive the share-price reaction. Investors rewarded the combination of rising traffic, higher tickets and the clearer profit trajectory rather than the headline revenue dip linked to the China transaction.
Related Articles
- United sees nearly $6bn fuel hit, profit tops estimates
- Hormuz reopens as two tankers carry 4m barrels
The next signpost is the fiscal year end on 28 September 2026, when Starbucks will report whether the Back to Starbucks strategy has sustained its momentum.
This article was created with AI assistance.