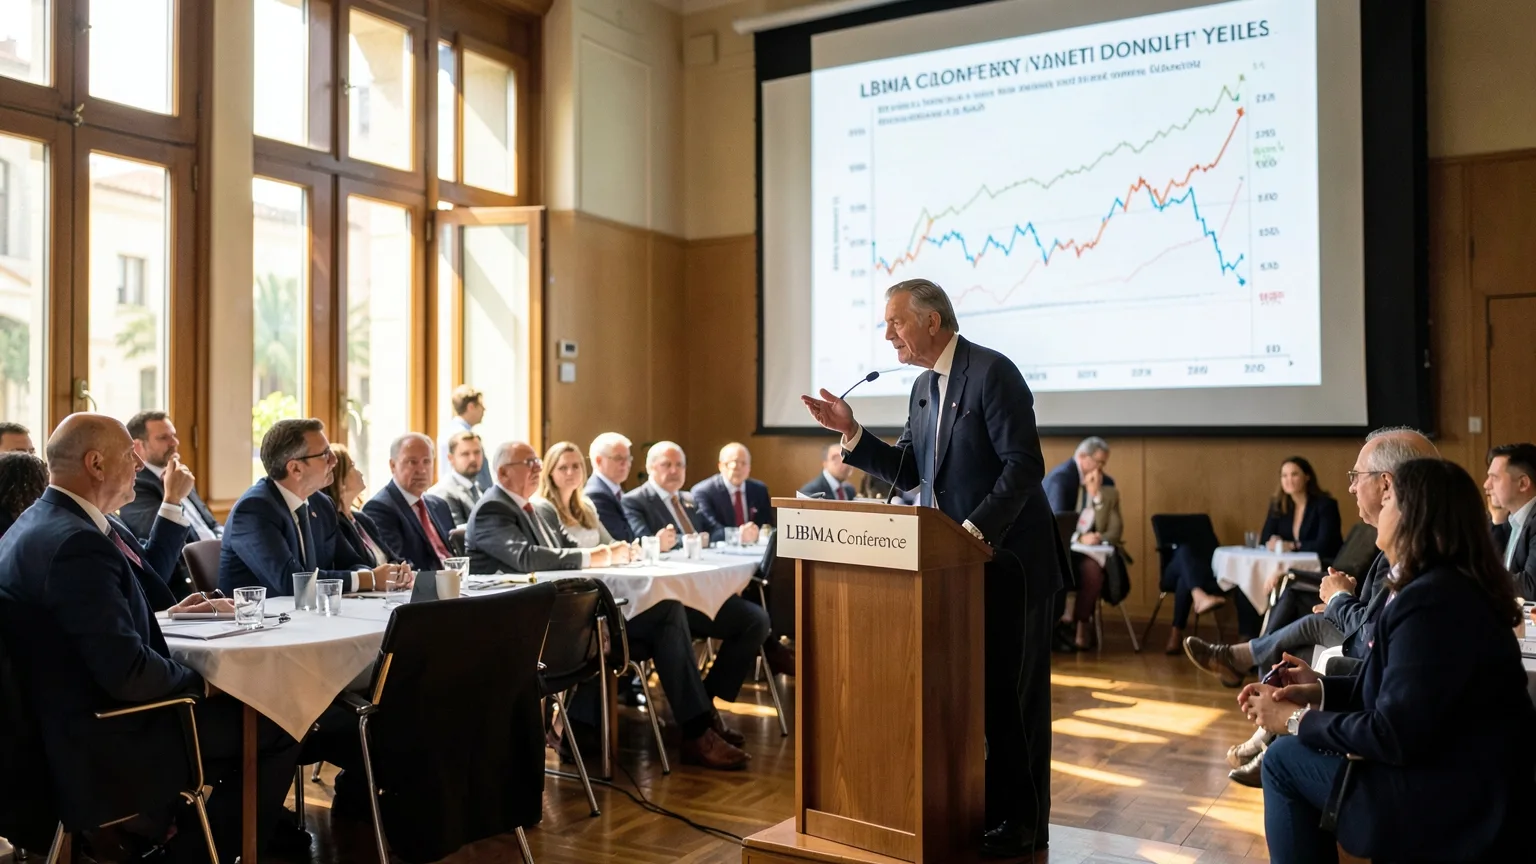
Senior central bankers told the LBMA conference in Sorrento that gold still serves as a diversifier and safe haven amid geopolitical and sovereign-debt risks, even though higher bond yields raise the opportunity cost of holding it.
Why central bankers still value gold
Senior central bankers at the LBMA conference in Sorrento said central banks still treat gold as a strategic reserve asset because it diversifies reserves and can act as a safe haven amid rising geopolitical risk and sovereign-debt concerns. Bank of Italy deputy governor Sergio Nicoletti Altimari said gold “is a safe haven asset, probably the safe haven asset,” arguing its historical performance across crises makes it a strategic reserve holding rather than a cyclical trade (www.reuters.com). He framed that role as particularly relevant today given “high geopolitical risk and concerns about economic fragmentation,” language he used to explain why central banks might look beyond yield when choosing reserve assets.
Bundesbank president Joachim Nagel said rising government bond yields have made sovereign debt relatively more attractive. He added, however, that the “case for diversification into gold remains significant” because geopolitical stress and the credit risk associated with high public indebtedness change the calculus for reserve managers.
Both officials described gold’s appeal as an assessment of what reserve managers need in a riskier geopolitical environment, while cautioning it won't protect portfolios in every scenario.
Higher yields change the calculation, not the role
Gold pays no interest, so higher bond yields raise the opportunity cost of holding it, and this year US Treasury yields have climbed to multi-decade highs. Reuters reported gold is down about 4% year-to-date while remaining above US$2,000 an ounce. That's the standard market calculation: when bonds pay more, non-yielding assets look relatively costly to hold.
Speakers said the practical link between real yields and gold has weakened recently. Altimari argued the market has undergone a structural shift since 2022 driven by central-bank purchases in emerging economies and by safe-haven buying, which “weakened gold’s traditional inverse relationship with real bond yields.” That is their explanation for why gold has remained relatively well supported even as yields rose; they did not present the historical relationship as permanently broken.
Reserve data show the scale, and its limits
In his keynote, Bundesbank president Joachim Nagel set the recent rise in gold’s share of reserves in historical context, saying that “from 2023 to 2025, the share of gold in global reserves jumped to almost 25 percent” and that the main driver of that jump was the sharp increase in the price of gold rather than proportional increases in physical holdings (www.bundesbank.de). He cited the IMF’s International Liquidity database for the series and emphasised that valuation effects (a rising gold price) can lift gold’s share of reserves even when the quantity of metal held changes little.
IMF figures for end-2025 do not produce a single headline percentage that matches every public report; Bundesbank's rounded “almost 25 percent” and its explanation that price moves drove much of the increase are the clearest data points in the material presented. Nagel also laid out the distinction central banks make between liquidity, safety and return when managing reserves, saying gold’s principal attraction is that physical bullion “does not depend on an issuer or counterparty fulfilling a payment obligation,” which matters when there are fears of asset freezes or sanctions.
Buying outlook and what it means for Ireland
Consultancy Metals Focus forecasts central-bank gold demand at about 720 tonnes in 2026, down roughly 15% year-on-year but still above pre-2022 levels; that figure was cited at the conference as a forecast rather than a final tally. Speakers used that outlook to argue central-bank buying may remain an important support for the price even if flows moderate.
For Irish readers, the practical takeaway is simple. Central banks continue to treat gold as a strategic reserve asset for diversification and geopolitical insurance, but that institutional role isn't the same as investment advice for individuals. Reserve-asset behaviour shouldn't be read as a prediction of future prices, and higher sovereign yields increase the opportunity cost of holding bullion.
This article was created with AI assistance.


